Key Technical Takeaway
A construction loan is a specialized mortgage where funds are disbursed incrementally across 5 or 6 construction stages (deposit, base/slab, frame, lockup, fixing, and practical completion) rather than as a lump sum. Borrowers pay interest only on the drawn balance during construction, keeping monthly holding costs lower until the build is completed.
Executing residential building projects requires navigating engineering standards, trade labor coordination, and municipal building codes. In modern construction, preventing budget overruns depends upon establishing technical specifications before works begin. Homeowners frequently overlook how soil conditions, load paths, and council zoning dictate both project duration and trade complexity.
Whether undertaking a major structural alteration or evaluating contract allowances, understanding trade sequencing protects your investment. In this technical guide, our licensed building team examines the engineering principles, compliance standards, and realistic cost benchmarks governing how construction loans work: milestone drawdowns, bank valuations and progress stages.
How Do Banks Calculate the ‘As-Complete’ Valuation of Your Property?
When analyzing how construction loans work, builders must trace how framing interfaces with structural loads. Structural modifications create concentrated point loads traveling downward through studs and footings. Failing to trace these load paths causes floor deflection and cracked plasterboard over time.
To preserve structural equilibrium, trades install engineered load-distribution beams. For instance, when homeowners calculate the bank progress inspections, experienced estimators account for temporary shoring and steel hardware. Engaging a licensed structural engineer guarantees deflection limits comply with residential building code tolerances.
Why Do Lenders Require Homeowners to Inject Their Own Cash Equity First?
Statutory regulatory compliance governs all residential construction. Before site demolition, builders must verify whether the project qualifies as exempt development, complying development (CDC), or mandates a full Development Application (DA). Unapproved work risks stop-work orders and fines.
Consulting our dedicated Construction Loans category provides guidance on zoning setbacks, certifier inspections, and contractor licensing. Cross-referencing architectural plans with structural schedules prevents contentious contract disputes during construction.
Technical Specifications & Cost Comparison Benchmark
The following benchmark illustrates standard industry costs, trade requirements, and statutory milestones for how construction loans work:
| Construction Loan Stage | Standard Drawdown % | Trigger for Fund Release | Inspection Required? |
|---|---|---|---|
| 1. Initial Deposit Stage | 5% of Contract Value | Signing contract & permit lodgement | No (Bank reviews executed contract) |
| 2. Base / Slab Poured | 10% – 15% of Contract Value | Footings dug, steel tied, concrete poured | Yes (Bank valuer site inspection) |
| 3. Framing Stage | 15% – 20% of Contract Value | Wall studs, roof trusses, floor joists erected | Yes (Valuer verifies frame completeness) |
| 4. Lockup Stage | 20% – 25% of Contract Value | Roof installed, brickwork/cladding, windows in | Yes (Building must be weather-tight) |
| 5. Fixing / Internal Linings | 20% – 25% of Contract Value | Plasterboard, cabinetry, plumbing/elec rough-in | Yes (Internal linings verified) |
| 6. Practical Completion | 5% – 10% of Contract Value | Painting, floorings, appliances, occupancy cert | Yes (Full final bank valuation audit) |
Source: Chris Cumbo Construction benchmark data. Excludes sales taxes.
What Causes Discrepancies Between Builder Payment Claims and Bank Valuations?
On-site execution demands strict quality control. Subcontractors must follow specified fastening schedules, screw gauges, and concrete curing durations. Coordinating handovers between carpenters, plumbers, and electricians prevents accidental damage to concealed services.
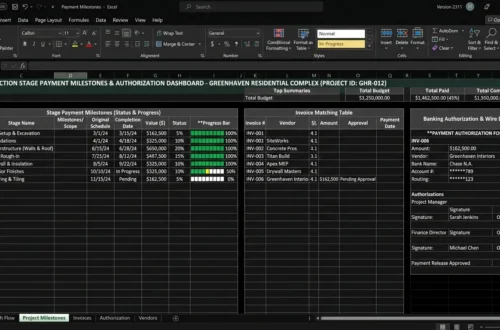
Homeowners should review documentation against construction drawdown percentage schedules to verify scope inclusions match milestones. Ensuring progress claims align with physical work safeguards your equity and prevents premature payments before defects are rectified.
Essential Homeowner Due Diligence Checklist
- Licence & Insurance: Verify active contractor licence, public liability cover, and home warranty insurance.
- Engineering Schedules: Obtain signed structural computations and footing inspection reports from a registered engineer.
- Written Variations: Enforce that every contract change is documented with itemized pricing before work starts.
- Certifier Sign-Off: Ensure your building certifier inspects and stamps every critical stage before payments are made.
Final Summary & Practical Guidance
Executing how construction loans work: milestone drawdowns, bank valuations and progress stages successfully requires balancing realistic budgeting with engineering oversight. By insisting on transparent contracts, independent certifier inspections, and trade-verified materials, homeowners protect their asset’s structural integrity. Consult a licensed builder or structural engineer before signing building contracts.
Furthermore, maintaining comprehensive photographic records across every milestone inspection provides incontrovertible evidence of code compliance before walls are closed and insulated. When homeowners archive date-stamped photographs of subfloor damp-proofing, structural tie-downs, and rough-in service penetrations, future property audits and insurance warranty evaluations remain completely transparent and straightforward.