Construction Loans
-
Builder Delays and Liquidated Damages: Understanding Delay Costs and Homeowner Legal Rights
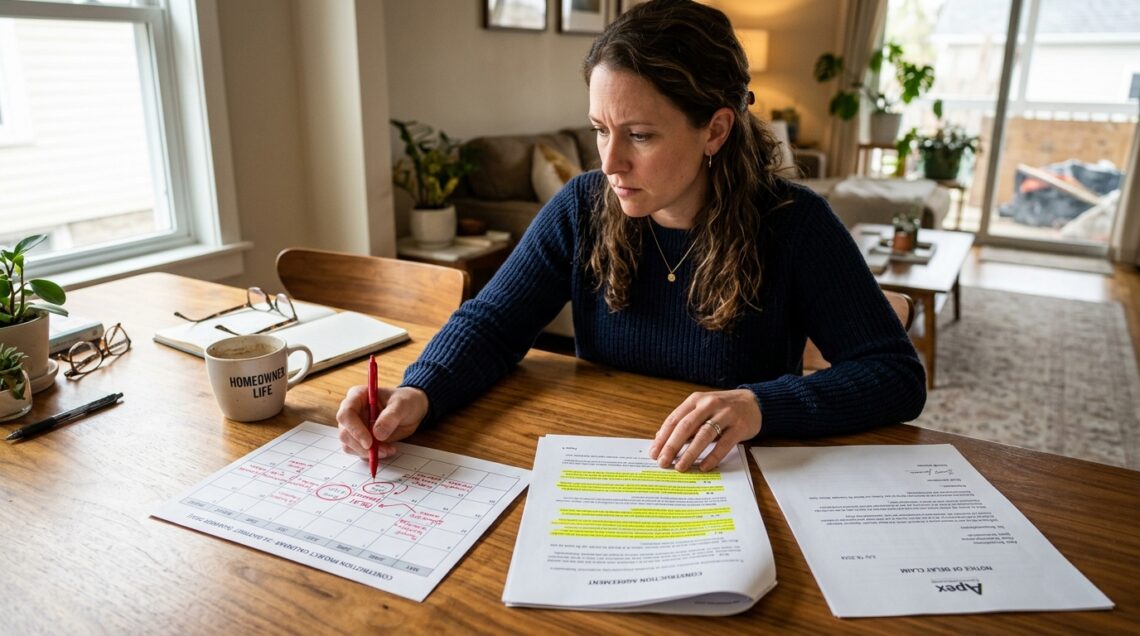
Liquidated damages are a pre-agreed daily or weekly rate stipulated in the building contract to compensate the homeowner if the builder fails to achieve practical completion by the contractual completion date. Typical rates range from $350 to $1,000 per week, reflecting actual holding costs such as rental accommodation, storage fees, and additional construction loan interest.
-
Construction Drawdown Percentage Schedules: Standard Industry Payment Milestones
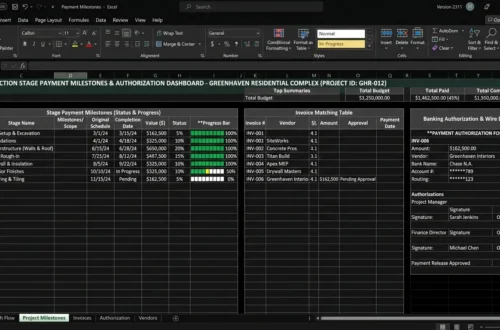
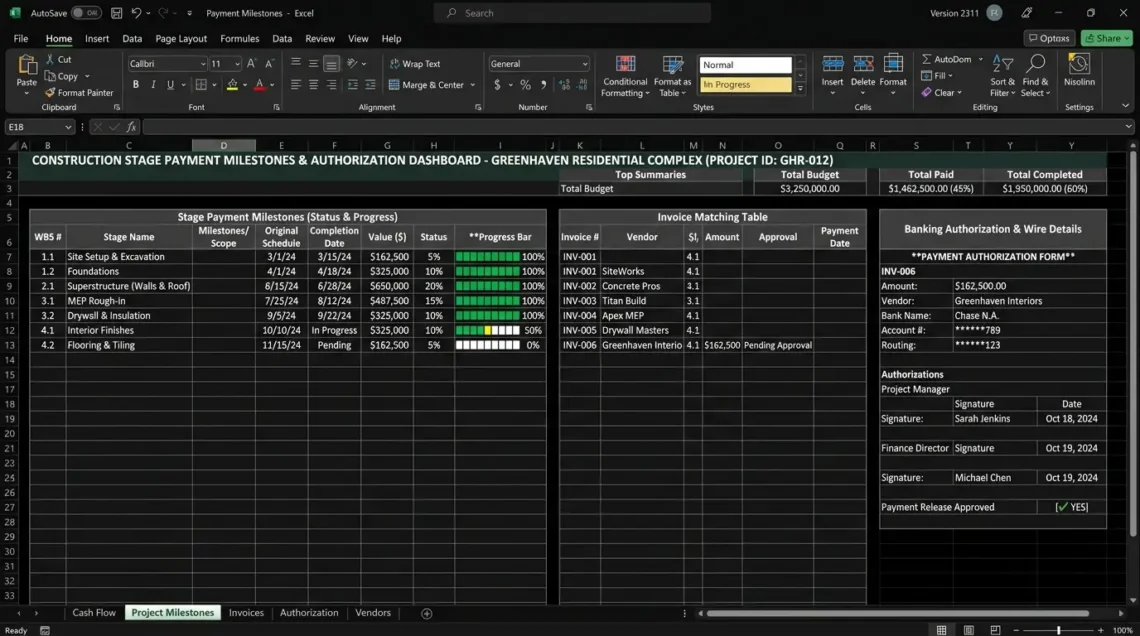
A construction drawdown percentage schedule dictates what proportion of the total contract price is payable at each milestone. Standard bank-approved schedules allocate: Deposit (5%), Base (10-15%), Frame (15-20%), Lockup (20-25%), Fixing (20-25%), and Practical Completion (5-10%). Front-loaded schedules, where builders demand large early payments, pose extreme financial risk to homeowners.
-
Bank Progress Inspections: What Valuers Inspect Before Releasing Progress Claim Funds
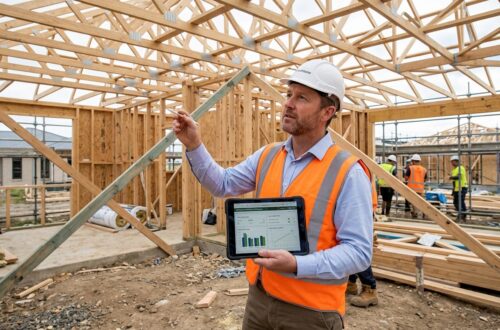
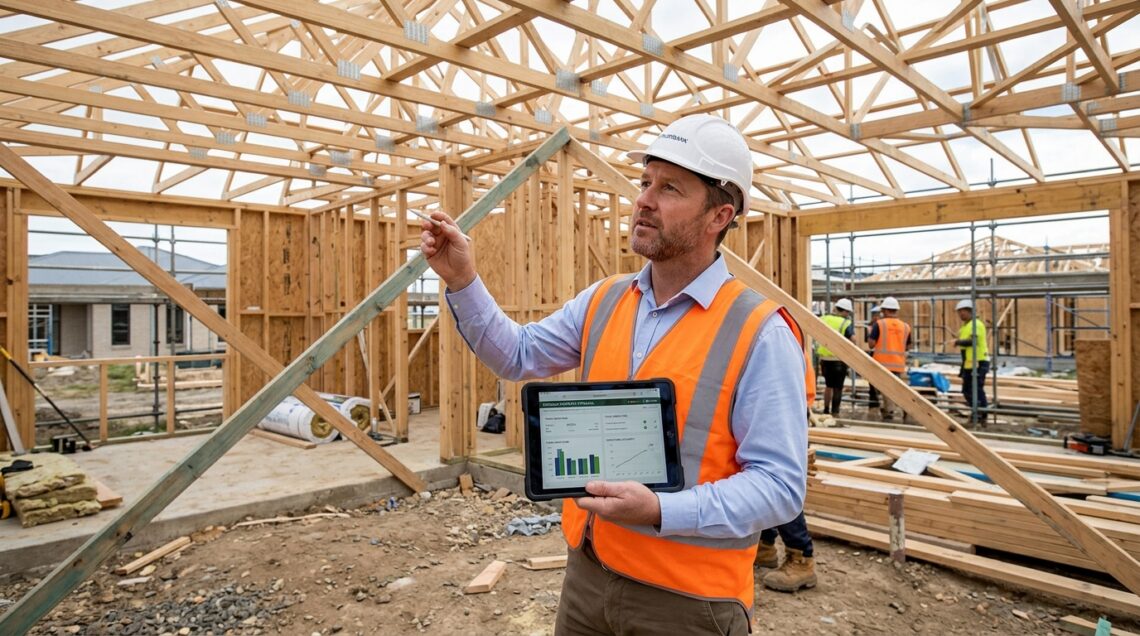
Before a mortgage lender releases funds for a progress claim, a bank valuer conducts a physical or photographic progress inspection to verify that the claimed milestone is 100% complete. If a builder claims 'lockup stage' but external doors or window flashings are uninstalled, the bank will refuse to release funds until the building is completely weather-tight.
-
How Construction Loans Work: Milestone Drawdowns, Bank Valuations and Progress Stages
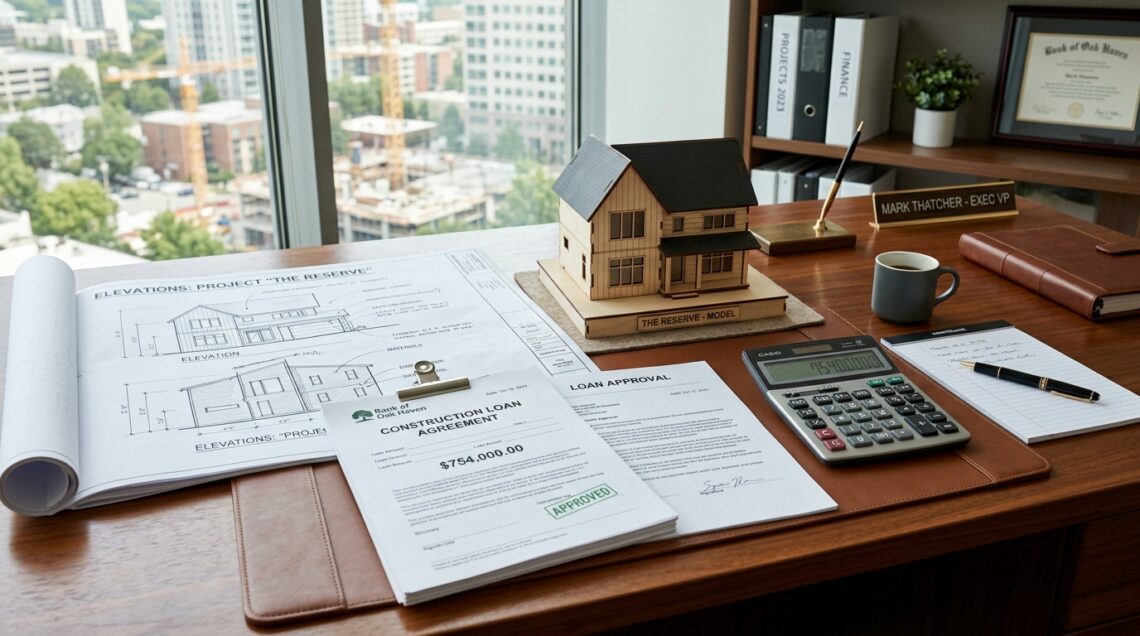
A construction loan is a specialized mortgage where funds are disbursed incrementally across 5 or 6 construction stages (deposit, base/slab, frame, lockup, fixing, and practical completion) rather than as a lump sum. Borrowers pay interest only on the drawn balance during construction, keeping monthly holding costs lower until the build is completed.